PRACTICAL GUIDE / NZ
Payment outage or account review: separate the two
 Partner campaigns: New ZealandUpdated 18 November 2026
Advertisement · 18+. Bonus, rating and review figures come from the campaign; they are not independently verified reviews. Check eligibility, availability and current terms. Listing does not establish local licensing.
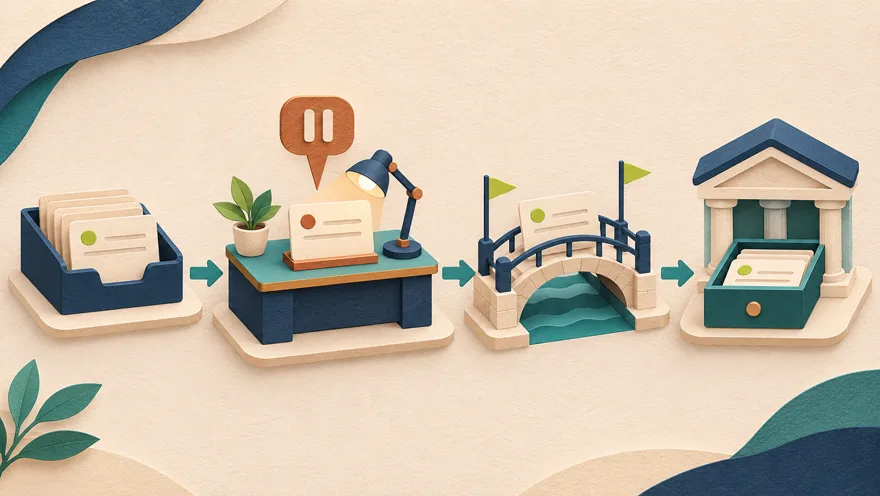
Use timestamps, transaction states and precise support questions to distinguish a broad payment incident from a review of one account.
Describe the symptom before assigning a cause
A deposit button that stops responding, a withdrawal marked under review and a bank transfer that has not arrived are different symptoms. Calling all of them an outage can send the enquiry in the wrong direction. Start with the smallest factual statement: what action was attempted, what the screen displayed, when it happened and whether any money changed position. Record the browser or app message exactly, without interpreting it as proof of a technical failure.
Check whether the account remains accessible and whether its history shows a new transaction. An error page is not evidence that no instruction was created. If a request exists, preserve its identifier and avoid submitting another one until its outcome is clear. If no request appears, ask support whether the attempt reached the payment system. This approach keeps a failed page load separate from a completed payment and gives the next person a useful place to begin investigating.
Read incident messages within their stated scope
A public maintenance notice may name a payment method, a service or a time window. Compare those details with your own case. A notice about card deposits does not explain a bank withdrawal made earlier, and a resolved incident does not prove every affected payment has been reconciled. Save the notice with its publication or update time, then ask whether your transaction is included in the incident.
Unofficial comments can suggest that other people have similar symptoms, but they cannot establish the status of your account. Do not publish your transaction identifier in a forum to seek confirmation. If support refers to an incident, ask for the relevant case or incident reference, whether your request is queued or failed, and what evidence will show that normal processing has resumed. A clear answer should distinguish service availability from the treatment of payments already in progress. Restoring a button and settling a previously submitted transaction are separate recovery tasks.
Identify the owner of the next decision
Ask which party is currently expected to act. The operator may need to complete an account review; its processor may need to reconcile a transaction; your bank may need to investigate an incoming payment. The answer can change during the case, so record when responsibility moved and what event triggered the move. A general statement that the issue is with the bank is not a substitute for identifying a payment that the bank can trace.
Where documents are requested, ask whether that request is independent of the reported service incident. A technical explanation should not be used to obscure an outstanding identity check, and an identity request should not be assumed to explain an unrelated outage. Supply required information only through the verified account channel and ask for confirmation of receipt. Do not send passwords, authentication codes or remote-access permission to someone claiming that an outage requires them. Those details are not ordinary evidence for a payment investigation.
Decide what can be checked without another deposit
After a service notice is marked resolved, you can review account access, transaction history and the existing request without creating a new paid transaction. A test deposit is poor evidence that an old withdrawal has been repaired: it uses a different instruction and may use a different payment route. Ask for the status of the original transaction and compare it with your own records instead.
If no meaningful update arrives within the timeframe the provider supplied for your case, move to its formal complaint channel with the timeline attached. State which factual question remains unanswered, such as whether funds were released or whether a failed attempt created a debit. Preserve incident notices because they may later disappear or change. When the case ends, keep the explanation alongside the outcome and check for duplicate instructions created during retries. Restoring access does not require you to keep gambling; leaving the account inactive while an existing payment is resolved avoids adding further movements to an already unclear ledger.
If the provider removes an incident notice, keep the copy you captured and its source address in your private notes. Do not present it as a current warning after the service has recovered; it is historical evidence about the period affecting your request.