Regulatory note: New Zealand’s Online Casino Gambling Act 2026 is in force, but the licensed market is being introduced in stages. DIA says the licensed regime is expected to become fully operational in 2027. Advertising is currently prohibited. From 1 December 2026, only operators entitled to continue through the licensing process may provide online casino gambling to people in New Zealand. Check the current DIA position before relying on any older article.
Start with the status you can actually see
| What you see | Who probably controls the next step | What to record | Useful next page |
|---|---|---|---|
| Deposit says “declined” and no debit appears | Bank, card issuer, wallet or processor | Time, amount, currency, exact message, last four digits only | Deposit declined |
| Deposit is pending or a debit appears without balance credit | Processor or operator reconciliation | Bank status, cashier status, transaction reference | Deposit declined |
| Withdrawal says “pending review” | Operator | Request ID, requested time, amount, KYC status, published timeframe | Withdrawal pending |
| Withdrawal says “processed” but money has not arrived | Payment network or receiving institution, if the operator can supply a real reference | Release time, method, currency, trace/reference | Bank transfer stages |
| Documents are requested | Operator compliance team | Requested document, reason, secure upload route, submission time | Payment verification |
| Amount received is lower | FX or fee may sit at operator, intermediary, wallet or bank | Gross amount, sent currency, received amount, all statements | NZD and conversion |
Do not post identity documents, full card numbers or bank statements in public forums. Do not make another deposit because somebody says it is needed to “release” an ordinary withdrawal. Ask for the exact written requirement and use the official secure account channel.
A four-stage model for withdrawals
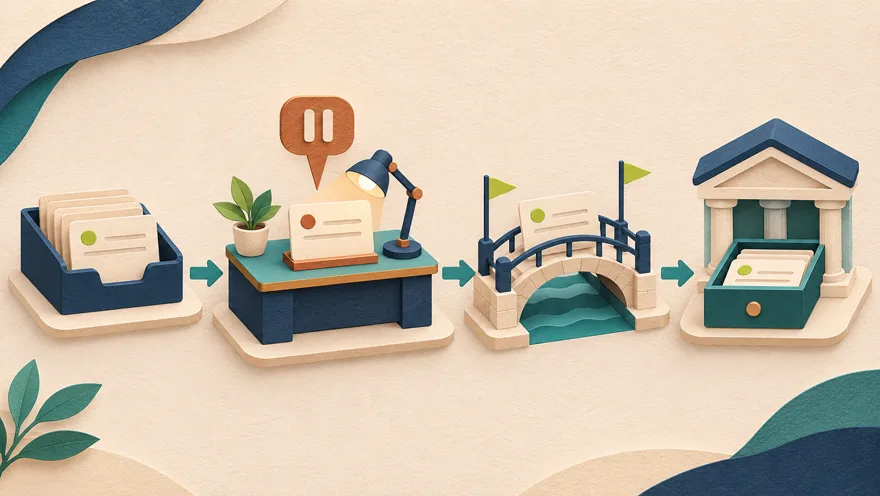
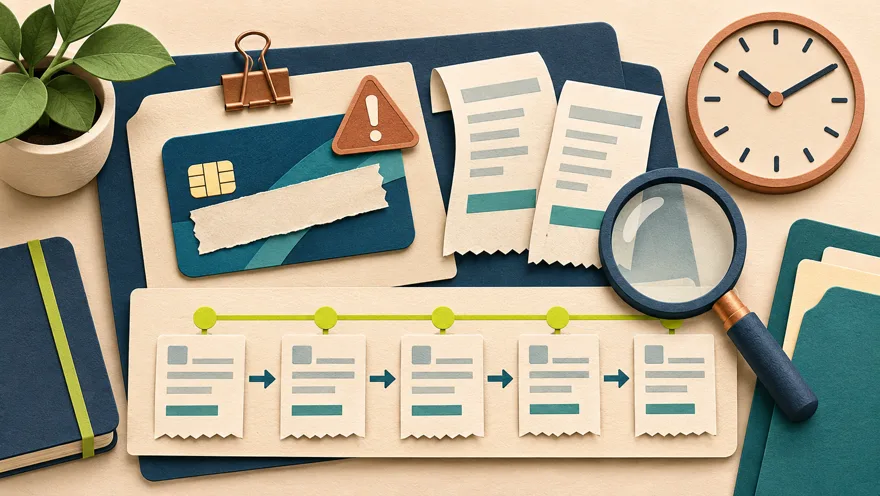
Treat a withdrawal as four separate clocks:
- Requested. The account has recorded your instruction. Funds may still be inside the operator’s system.
- Reviewed. Identity, payment ownership, account restrictions, game/bonus conditions or a risk check may be examined. “Pending” usually describes this stage, but terminology varies.
- Sent. The operator says it has released the payment. Ask for the payment method, release time and a traceable reference. A generic “processed” message is not the same as a bank reference.
- Settled. The receiving bank, card or wallet credits the funds. Currency conversion and intermediary charges may become visible only here.
New Zealand electronic payments between participating domestic banks have been processed seven days a week since May 2023. That fact does not prove that an offshore casino reviews withdrawals on weekends, that an international payment uses the domestic system, or that a wallet-to-bank transfer is instant.
A three-part check for deposits
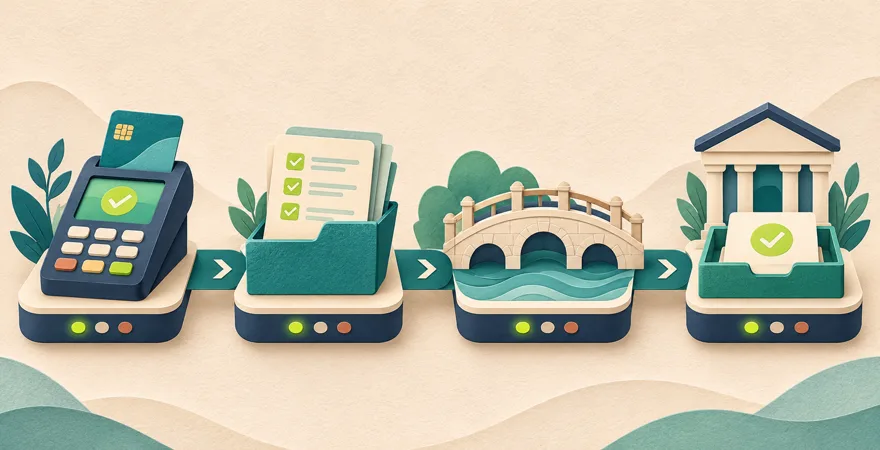
1. Is it a real decline or a temporary authorisation?
Compare the cashier status with the bank or wallet status. A declined payment with no debit is different from a pending card authorisation. If a pending entry later disappears, the funds may simply have been released rather than refunded. Preserve the wording before retrying.
2. Does the payment identity match the account?
The name on the gambling account, bank account, card or wallet normally needs to belong to the same person. A mismatch, joint account, virtual card or third-party payment can trigger ownership questions. Do not alter documents or route funds through somebody else.
3. Is a deliberate restriction working as intended?
A bank gambling block, self-exclusion control, deposit limit or platform restriction is a safety feature. We do not provide instructions for evading one. If a block was enabled intentionally, leave it in place. If you are unsure why it exists, contact the bank or operator and ask for the category of restriction without asking them to remove it.
What New Zealand’s new rules change
For the future licensed regime, the 2026 Regulations require an operator to verify identity and that the customer is at least 18, prohibit payment methods involving a credit contract, allow a different registered withdrawal method where return to the deposit method is not possible, and require uncommitted funds to be returned without undue delay after legal requirements are met. The Regulations also limit an account to one registered deposit method at a time and prevent a change within 24 hours of registration.
Those standards should not be projected backwards onto every offshore service during the transition. On the check date, the DIA public licence register for the new regime was not yet the basis for this site. This site therefore does not label, rank or link to “approved NZ casinos”.
The evidence pack to keep
Create a private timeline containing:
- account name and masked account identifier;
- transaction amount and currency;
- deposit or withdrawal request time in New Zealand time;
- every status change and its time;
- transaction or withdrawal ID;
- the published term that was visible when you acted;
- what the operator asked for and when you supplied it;
- chat/email case numbers;
- a payment trace or bank reference after the operator says funds were sent.
Screenshots prove what a screen displayed at that moment. They do not prove a payment reached a bank. Likewise, a bank cannot trace money that the operator has not actually released.
Choose the guide that matches your task
- Compare deposit and withdrawal methods when you have not paid yet.
- Diagnose a declined deposit when the cashier or bank refuses a payment.
- Diagnose a pending withdrawal when a request is still under review or apparently sent.
- Understand bank-transfer stages when the payout should land in a bank account.
- Prepare payment verification when identity, address or method ownership is being checked.
- Read fees and limits before treating “no fee” as a full-cost claim.
- Check the current NZ law before relying on an operator list or an older legal summary.
When to treat a delay as a warning sign
A delay alone does not prove wrongdoing. Escalate your caution if the published time has passed and support will not identify the stage; document requests keep changing without a clear reason; the balance repeatedly returns and is re-requested; terms are applied retroactively; or anyone asks for a new deposit, tax, insurance or “unlock fee” before releasing existing funds. Keep your evidence and use the operator’s formal complaint route and the regulator named in its current terms. The NZ complaint route for licensed operators will depend on the new DIA regime and public register.
Frequently asked questions
Is online casino gambling legal in New Zealand?
The legal position changed in 2026 and is in transition. The Online Casino Gambling Act 2026 creates a licensed market, with phased implementation through 2027. Read the current-law explainer and the DIA page on the day you need the answer.
What is the fastest withdrawal method?
No payment rail can make the operator’s review instant. A wallet may credit quickly after release, while a bank transfer may add settlement and FX steps. Compare the full path, not a single advertised number.
Does “processed” mean my bank has the money?
Not necessarily. Ask whether funds were released, which network was used, and for a reference the receiving institution can trace.
Can I use another person’s card or bank account?
Do not. Third-party payment details create ownership and compliance problems and can breach terms. Use only a method in your own name and follow the official verification process.
Where can I get help with gambling harm?
Safer Gambling Aotearoa lists the free 24/7 Gambling Helpline at 0800 654 655 and free text 8006. If continuing to troubleshoot payments is keeping you engaged in gambling, stop and contact support.